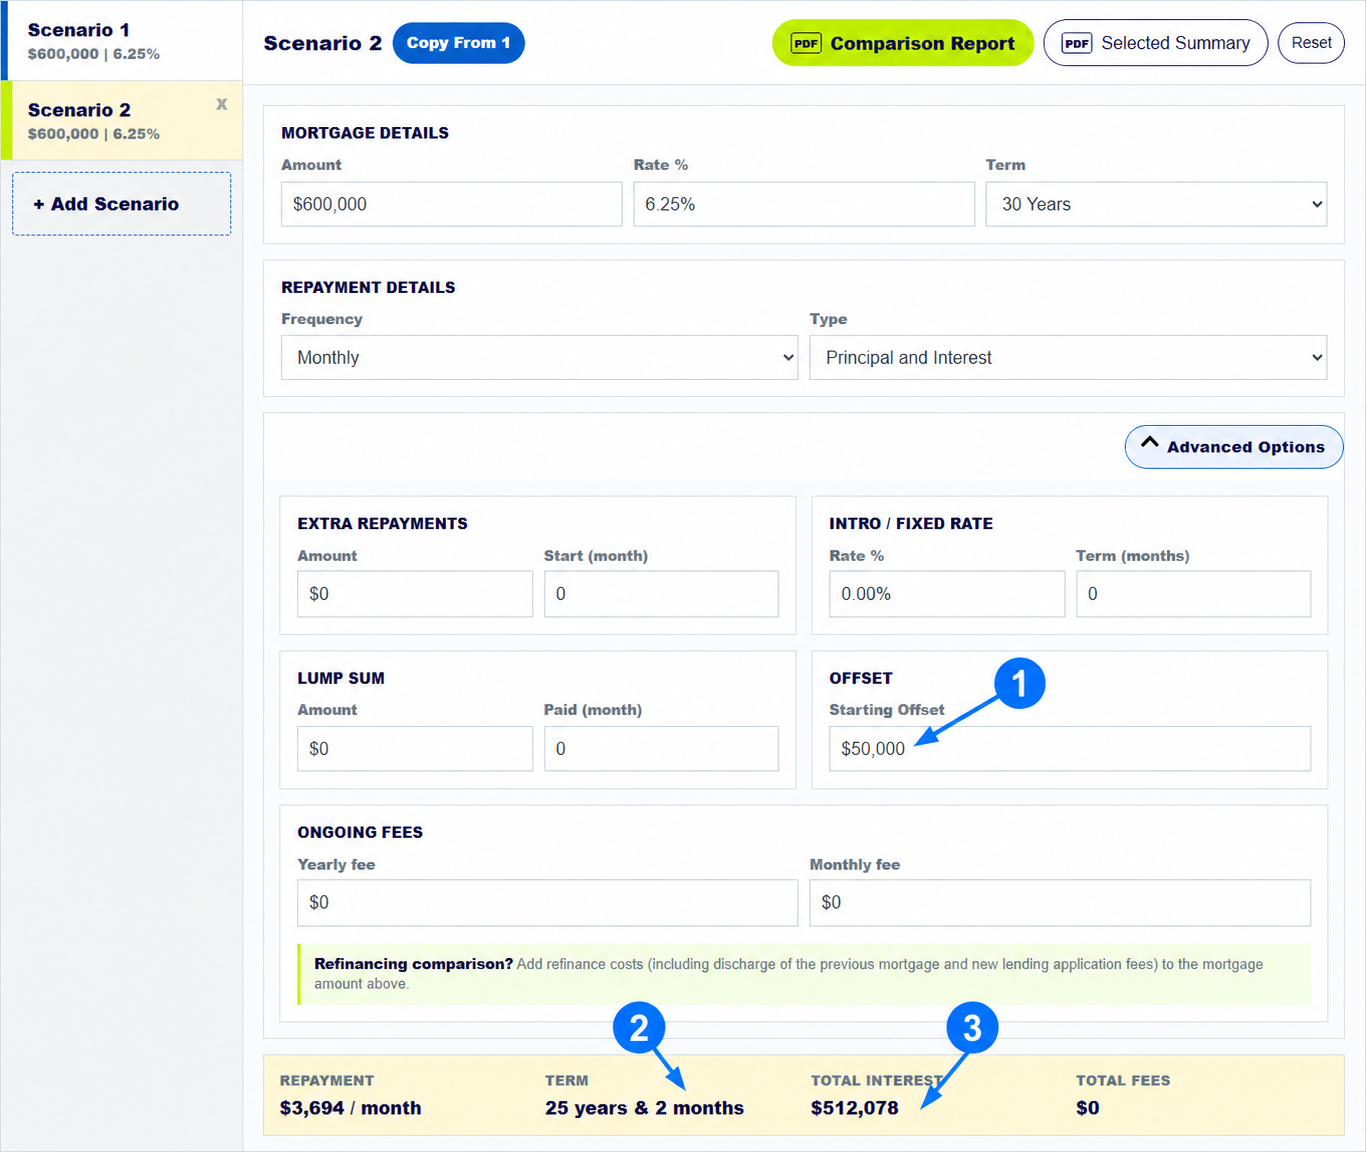
To estimate the effect of an offset account, enter your home loan in Scenario 1, copy it into Scenario 2, then put the amount you expect to keep in the linked account in Starting Offset. The calculator keeps that money separate from the loan principal while modelling less interest. It then shows how the projected interest and term change.
The numbered arrows on the real calculator screenshot above show the controls used in this example. Open the calculator to enter your own figures.
How does an offset account reduce mortgage interest?
An offset account is a separate account linked to an eligible home loan. Its balance is used to reduce the loan balance on which interest is calculated. For example, if a loan balance is $600,000 and a full offset holds $50,000, interest may be calculated on $550,000 while that balance is held. The loan itself still starts at $600,000; the offset is not a $50,000 repayment.
Check the lender's product rules. Offset arrangements can differ, and ASIC advises borrowers to check that an offset is linked correctly and delivering the expected benefit.
How do you enter a starting offset balance in the calculator?
Use Add Scenario and Copy From 1 so the loan amount, rate, term and payment frequency match. In Scenario 2, open Advanced Options and enter the balance under Offset: Starting Offset. Leave other changes at zero for a clean comparison. If the loan with an offset has a different rate or an annual package fee, add those too before comparing products.
This tool models a starting offset balance. It does not model every deposit and withdrawal in a changing transaction account, so treat the result as a steady-balance illustration.
What could a $50,000 offset do to a $600,000 mortgage?
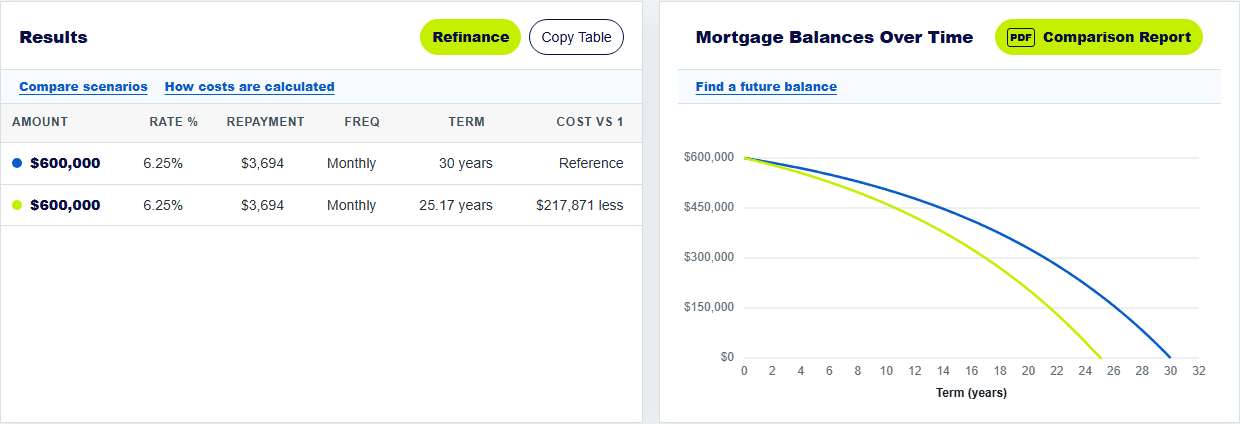
With a $600,000 loan at 6.25% over 30 years, the baseline calculator estimate is about $729,949 in total interest. Holding a modelled $50,000 starting offset in Scenario 2 gives about $512,078 in interest and a projected term of 25 years and 2 months, assuming the scheduled repayment remains about $3,694 a month. The estimated interest difference is $217,871.
That large difference depends on keeping the offset balance in place for the modelled period. If the balance is much lower most months, the real benefit will be smaller.
How do you compare offset fees with interest saved?
A loan with offset access may charge a higher interest rate or ongoing fee than a loan without it. Enter the actual rate, Yearly fee and Monthly fee for each option. Then compare total fees as well as interest and the projected term. A feature that saves interest can still be poor value if it costs more than it saves for your typical offset balance.
Ask the lender whether the account is a full or partial offset, which loan it is linked to and whether the benefit continues after refinancing or changing products.
Keep exploring: extra repayments guide, home loan comparison guide. For home-loan product conditions, see ASIC's offset account checklist.
Model your mortgage offset
Use the balance you expect to keep in the account, then add any extra product fees.
How does the mortgage calculator estimate offset savings?
How does the mortgage calculator treat money in an offset account?
It keeps the offset separate from the loan principal and uses the starting offset balance to reduce modelled interest. The money is not treated as a repayment.
Can the home loan calculator track changing offset balances?
No. It models a starting offset balance, not each deposit or withdrawal. Actual savings can therefore differ.
Where do I include offset account fees in the calculator?
Enter the relevant yearly or monthly fee in the scenario, then compare the cost with the modelled interest saving.
About this example: The illustration is a $600,000 principal-and-interest loan at 6.25% over 30 years with monthly payments. Scenario 2 models a $50,000 starting offset maintained in the example, with no extra fees or rate difference. Screenshots were captured from this calculator on 30 September 2026. Numbered arrows highlight important parts of the featured image. Results are estimates, not a lender quote or personal financial advice. Read the calculator assumptions.